

Strategic Intelligence for Global Impact
Explore our strategic thinking, practical frameworks, and client transformation stories, designed to help ambitious organizations navigate global challenges and unlock breakthrough results.
Featured Insight
International Development
Study on Taxation and Fiscal Policies Impacting the Mining and Metals Sector
This report examines how mining taxation and fiscal policy shape investment, government revenue and long-term sector competitiveness, using a comparative assessment of fiscal regimes across Australia, Chile, Peru, South Africa and Zambia and a standardised copper-mine financial model tested under multiple commodity-price scenarios.
Thank you! Your submission has been received!
Oops! Something went wrong while submitting the form.

Why Global South Investment Keeps Stalling Between the Pitch and the Signature
When a Global South government reaches the investment negotiation table, the investor on the other side typically arrives with a Tier 1 legal team specialising in cross-border infrastructure transactions, a financial advisor with a track record in the specific instrument and sector in question, and an investment committee that has seen dozens of comparable deals in comparable markets. The government counterpart often arrives with a generalist legal team, overextended treasury or ministry officials managing multiple competing priorities, and no institutional memory of what the last five transactions of this type actually delivered because deal terms are rarely published, rarely reviewed, and rarely used to inform the next negotiation.
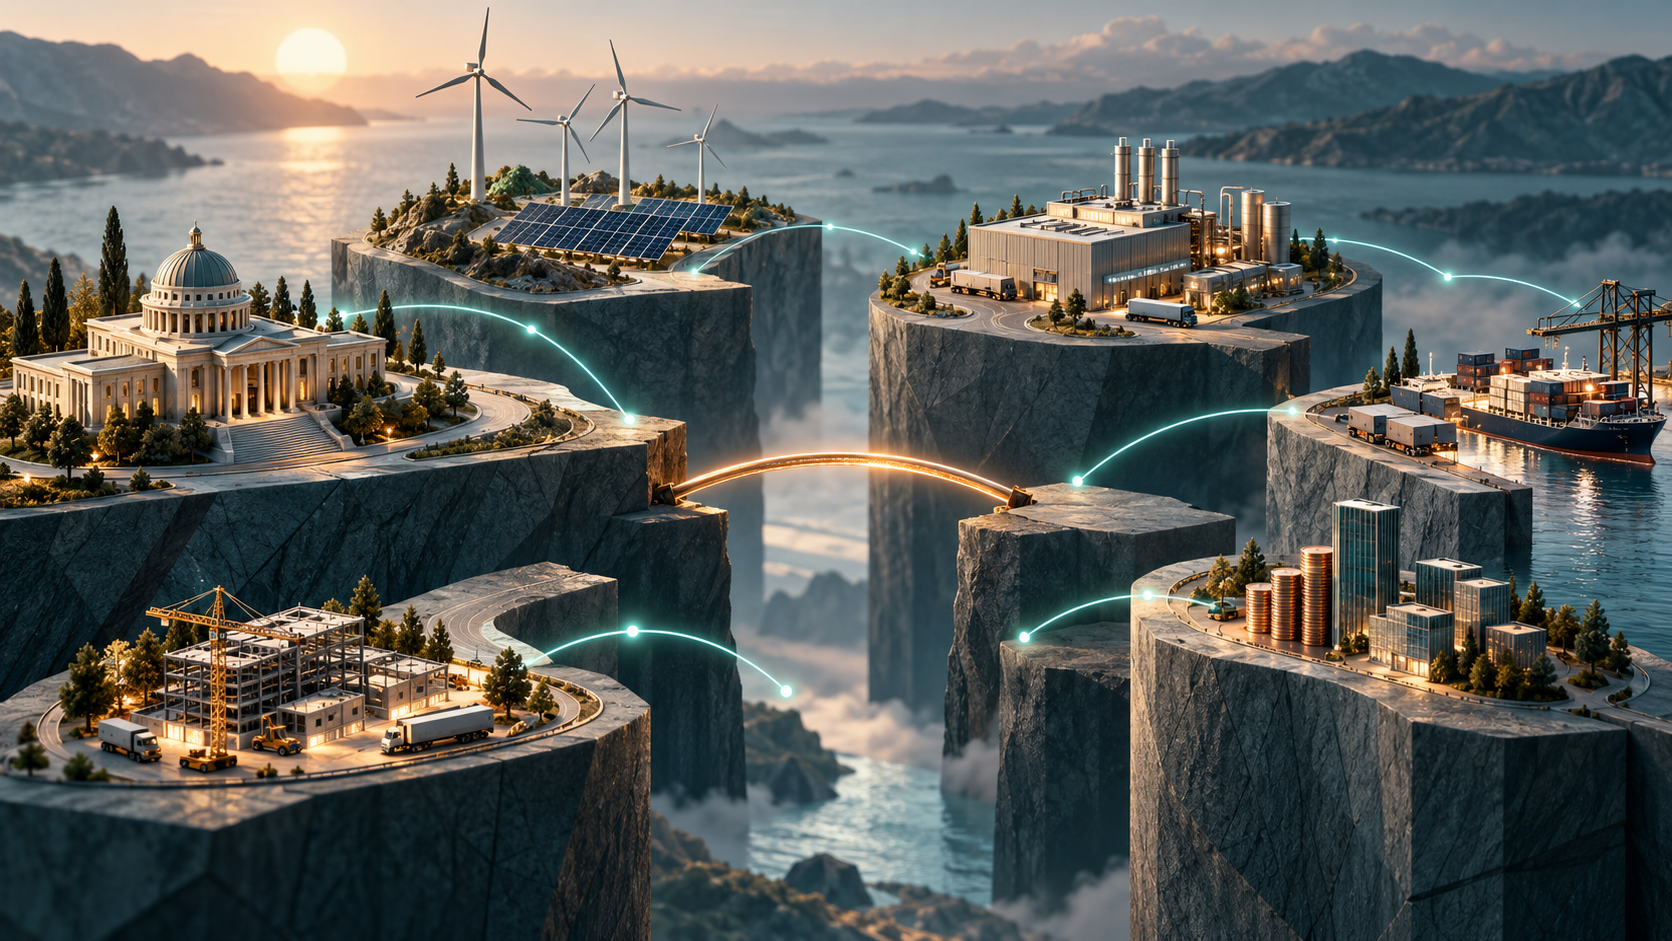
The Clean-Tech Intelligence Gap
By 2030, the clean technology market may be significantly larger without its underlying supply chains becoming significantly more diverse. The International Energy Agency projects no major improvement in the diversity of clean-energy technology supply chains before the end of the decade, based on committed manufacturing and mining projects and current market trajectories. While the transition continues to attract capital, expand manufacturing and reshape industrial priorities, many of the dependencies beneath it could remain largely intact.
The Second Phase of Supply-Chain Resilience
Businesses are entering a different phase of supply-chain resilience. The first response to disruption was largely geographic, with relocation, nearshoring, friendshoring and diversification becoming the dominant ways to reduce concentration and create alternatives as global trade became less predictable. That response still has value, but the pattern in 2026 is changing. Ninety-five per cent of businesses expect to adjust their supply-chain activities over the next three to five years, yet 59% expect neither to enter nor exit markets. Businesses are preparing for further disruption without necessarily changing where they source, manufacture or sell. The competitive shift is beginning to happen within the networks they already operate. This has transformed supply-chain resilience from a predominantly location-led strategy into a capability-led one. Businesses can operate across similar markets, suppliers and trade corridors while carrying materially different levels of exposure, depending on the visibility, financial coordination and response capacity operating beneath those networks.